Published by Panhandle Real Estate Investments, a locally owned real estate solutions company serving Bay County, Okaloosa County, Santa Rosa County, and Escambia County. We buy houses and land across the Florida Panhandle.
Last Updated: September 21, 2026
If you have a Citizens policy on a Panama City, Pensacola, or Crestview home, there is a good chance a letter has already landed telling you a private insurer wants to take over your coverage. That letter is a depopulation takeout offer, and it puts a real decision in front of you: accept the private policy, or try to stay with Citizens.
The catch is that the choice is not always yours. Florida changed the rules, and for a lot of policyholders the offer is not really optional once the numbers line up a certain way. Getting this wrong can mean a surprise premium jump, or a coverage problem that surfaces at the worst possible time, when you are trying to sell.
This guide explains what a takeout offer actually is, when you can opt out and when you cannot, and what the whole thing means if selling the house is anywhere on your radar.
Key Takeaways
- A takeout offer is a private insurer offering to assume your Citizens policy. Citizens runs a depopulation program to move policies into the private market.
- You can often opt out and stay with Citizens, but not always. One rule decides it.
- The 20 percent rule is the whole game. If the private offer is within 20 percent of your Citizens renewal premium, the policy is not eligible to renew with Citizens.
- A takeout does not transfer to your buyer. A financed sale still needs the buyer’s own policy, which is where a hard-to-insure home stalls.
- A cash buyer closes without any policy at all, so a takeout, a premium jump, or a coverage gap does not block the sale.
Table of Contents
- What a Citizens depopulation takeout offer is
- The choice: accept, or opt out
- Your options if you are thinking about selling
- How selling to Panhandle Real Estate Investments works
- Bay, Escambia, and Okaloosa County specifics
- Frequently asked questions
What a Citizens Depopulation Takeout Offer Is
A takeout offer, sometimes called an assumption, is when a private insurance company offers to take over your Citizens policy and cover your home instead. It is not a scam letter and it is not junk mail. It is part of a formal state program, and the carrier named in the notice is a real one that has agreed to insure your property.
Citizens is the state backed insurer of last resort, and it was never meant to hold millions of policies. To bring that number down, Citizens runs a depopulation program that matches policyholders with private carriers willing to assume their coverage. When a carrier picks up your policy, you get a notice with the new company name and the premium they intend to charge.
None of this happens in a vacuum. Premiums across the region have been climbing for years, and the takeout push is part of the same story, which is worth understanding alongside how Panhandle insurance costs have moved. A takeout can be a good thing, since private coverage often carries lower hurricane assessment risk than Citizens. The problem is the fine print on whether you are even allowed to say no.
The Choice: Accept, or Opt Out
In the past, a Citizens policyholder could simply decline a takeout offer and stay put. That is no longer guaranteed, and the reason is a single rule that came out of Florida’s 2022 insurance changes.
Here is the rule that decides it. Under Citizens’ current rules, a private offer within 20 percent of your Citizens renewal premium ends your eligibility to renew with Citizens. In Citizens’ own words, any policy a private insurer offers to cover for a premium “not more than 20% greater than the estimated renewal premium” of the Citizens policy “will not be eligible for renewal” with Citizens.
So the math, not your preference, usually settles it. If the private offer comes in within that 20 percent band, you cannot stay with Citizens, even if you would rather. If the private premium is more than 20 percent higher than your Citizens renewal, you can opt out and keep Citizens for now.
Quick accept-or-opt-out guide
- Private offer within 20 percent of your Citizens renewal? You cannot stay with Citizens. Compare the private policy’s coverage and hurricane deductible, then decide whether keeping the home still makes sense.
- Private offer more than 20 percent higher? You can opt out and keep Citizens, but expect that gap to keep pressuring your premium at future renewals.
- Planning to sell soon either way? Get an as-is cash number first, because a cash sale sidesteps the entire insurance question.
- Home already hard to insure at any price? That is the uninsurable path, and selling as-is is often the cleanest exit.
Your Options If You Are Thinking About Selling
A takeout offer often lands right when someone is already wondering whether to keep the house at all. If a rising premium or a shaky coverage situation is pushing you toward selling, you have three honest paths.
Keep the home and take the coverage. If the private policy is affordable and the home is easy to insure, accepting the takeout and staying put is perfectly reasonable. This post is not an argument against that. It only matters differently when the premium math or the home’s condition makes staying expensive.
List it on the open market. You can sell the traditional way, but remember the policy does not transfer cleanly to your buyer. Your buyer still has to secure their own coverage, and if the home is hard to insure that can stall or kill a financed deal, which is what happens when coverage disappears entirely.
Sell directly to a cash buyer. A cash buyer does not need a new policy to close, so the whole takeout question stops mattering. If your home is in Okaloosa County you can sell your Crestview house as-is without sorting out coverage first, and the insurance problem simply transfers to a buyer built to handle it.
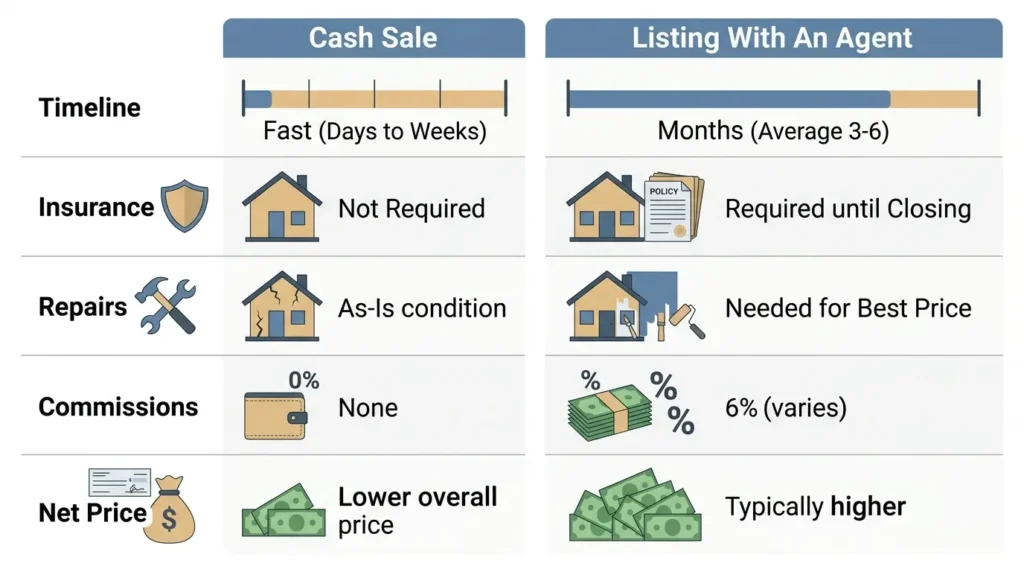
| Factor | Cash Sale (As-Is) | Listing With an Agent |
|---|---|---|
| Timeline | Often within a few weeks | Typically 60 to 120 days or more |
| Buyer needs insurance? | No, no policy required to close | Yes, the lender requires a policy |
| Effect of a hard-to-insure home | Priced in, does not block the sale | Can stall or kill a financed deal |
| Repairs | None | Often needed to list and to insure |
| Commissions | None | Typically 5 to 6 percent |
| Certainty of close | High | Subject to financing, insurance, inspection, appraisal |
| Net price | Below market, minus no repair bills | Closer to market, before the costs |
If you are still weighing keep versus sell, we maintain an honest comparison of your selling options that lays out the tradeoffs without the sales spin. The right answer is whichever path nets you the most once the insurance picture is settled, not whichever headline number looks biggest.
How Selling to Panhandle Real Estate Investments Works
If a cash sale turns out to be the right exit, the process is short and there is no obligation to accept anything.
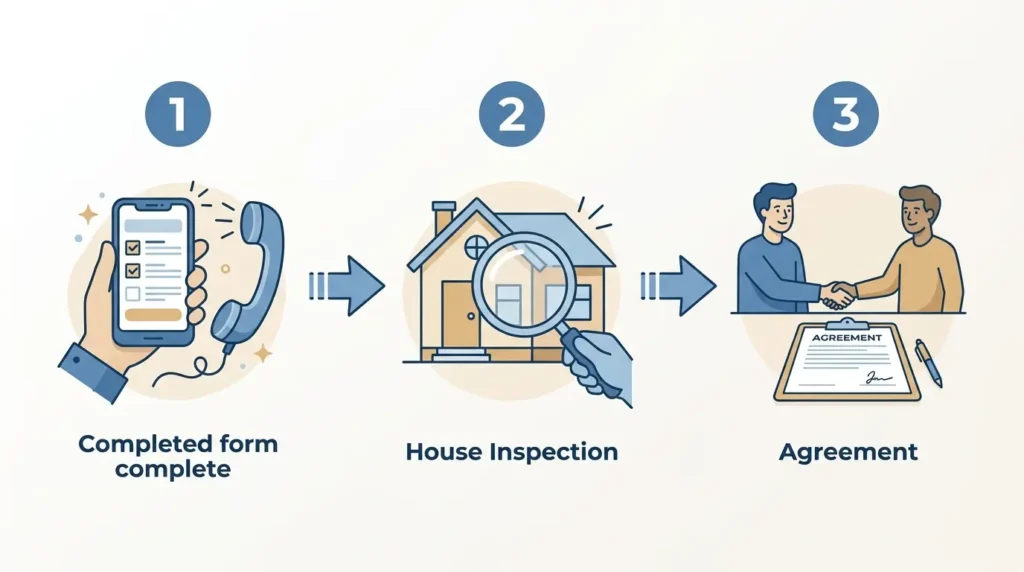
- Request an offer. Tell us about the home and where things stand with your coverage or your takeout notice. It takes a few minutes and there is no commitment.
- We look at the home and the numbers. We estimate any repairs and build them into a fair cash offer, with the math shown rather than hidden. The insurance situation does not scare us off.
- Close on your timeline. If the offer works, we handle the paperwork and close when you are ready, with no new policy to secure and nothing to repair first.
Not every owner should sell. If the takeout is affordable and you want to stay, keep the home and take the coverage. We will tell you plainly when staying is the better move for your situation.
Bay, Escambia, and Okaloosa County Specifics
The Panhandle’s coastal counties carry a heavy concentration of Citizens policies, so Panama City, Pensacola, and Crestview homeowners are seeing takeout offers in large numbers. Near-coastal wind exposure is exactly what pushed so many of these homes into Citizens in the first place, and it is the same reason private carriers are now selective about which ones they will assume.
That local pattern cuts both ways. If a private carrier wants your home and the offer lands inside the 20 percent band, you are moving to the private market whether you planned to or not. If no private carrier wants it, you may be stuck with Citizens or, in the worst case, looking at a home that is genuinely hard to insure.
It also means local cash buyers already understand these policies and these homes. A takeout letter, a premium spike, or a coverage gap on a Bay, Escambia, or Okaloosa County home is routine to an investor, not a dealbreaker. If the insurance picture is what is pushing you to sell, that is the part of the market that stays open to you.
Frequently Asked Questions
What is a Citizens depopulation takeout offer?
A takeout offer is when a private insurer offers to assume your Citizens policy and cover your home instead. Citizens runs a depopulation program that matches policyholders with private carriers, because state law pushes coverage out of Citizens and into the private market. You receive a notice naming the carrier and the premium they intend to charge.
Do I have to accept a takeout offer from Citizens?
Usually you can opt out and stay with Citizens, but not always. Under Florida’s rules, if the private offer is within 20 percent of your Citizens renewal premium, the policy is no longer eligible to renew with Citizens, so opting out is off the table. If the offer is more than 20 percent higher, you can decline it and keep Citizens.
What happens if the takeout premium is higher than Citizens?
It depends on how much higher. If the private premium is within 20 percent of your Citizens renewal, you lose Citizens eligibility and take the private policy. If it is more than 20 percent higher, you can opt out and stay with Citizens for now. Either way, the cost of keeping the home may rise at renewal.
Does a takeout affect my ability to sell the house?
Not directly, but it changes the math for a buyer. The policy does not transfer cleanly, so your buyer still has to secure their own coverage, and if the home is hard to insure that can stall a financed sale. A cash buyer does not need a new policy, so a takeout or a coverage gap does not block the deal.
Can I go back to Citizens after accepting a takeout?
Sometimes, but not freely. If your private premium later climbs or the carrier drops you, you may requalify for Citizens when no private offer keeps you inside the 20 percent window. Citizens is the insurer of last resort, so you generally return only when the private market will not cover the home affordably.
A takeout offer narrows your choices, it does not have to trap you. Whether you keep the home and take the coverage, or decide the insurance headache is your signal to sell, the right move comes down to your numbers, and knowing the as-is value is the fastest way to see them clearly.
If you want to know what your Panama City, Pensacola, or Crestview home is worth as-is, takeout letter and all, we are happy to give you a straightforward answer. No obligation, no pressure. Request a cash offer from Panhandle Real Estate Investments.
About Panhandle Real Estate Investments
I’m Peyton Saluto, founder of Panhandle Real Estate Investments. For over seven years, I’ve helped homeowners across the Florida Panhandle find fair and stress-free ways to sell their homes—no repairs, no commissions, and no pressure. My goal is always to put people first and make a real difference in our communities by restoring distressed properties and rebuilding neighborhoods. If you’re thinking about selling, reach out for a no-obligation cash offer. I’d love the opportunity to help you find the best path forward.